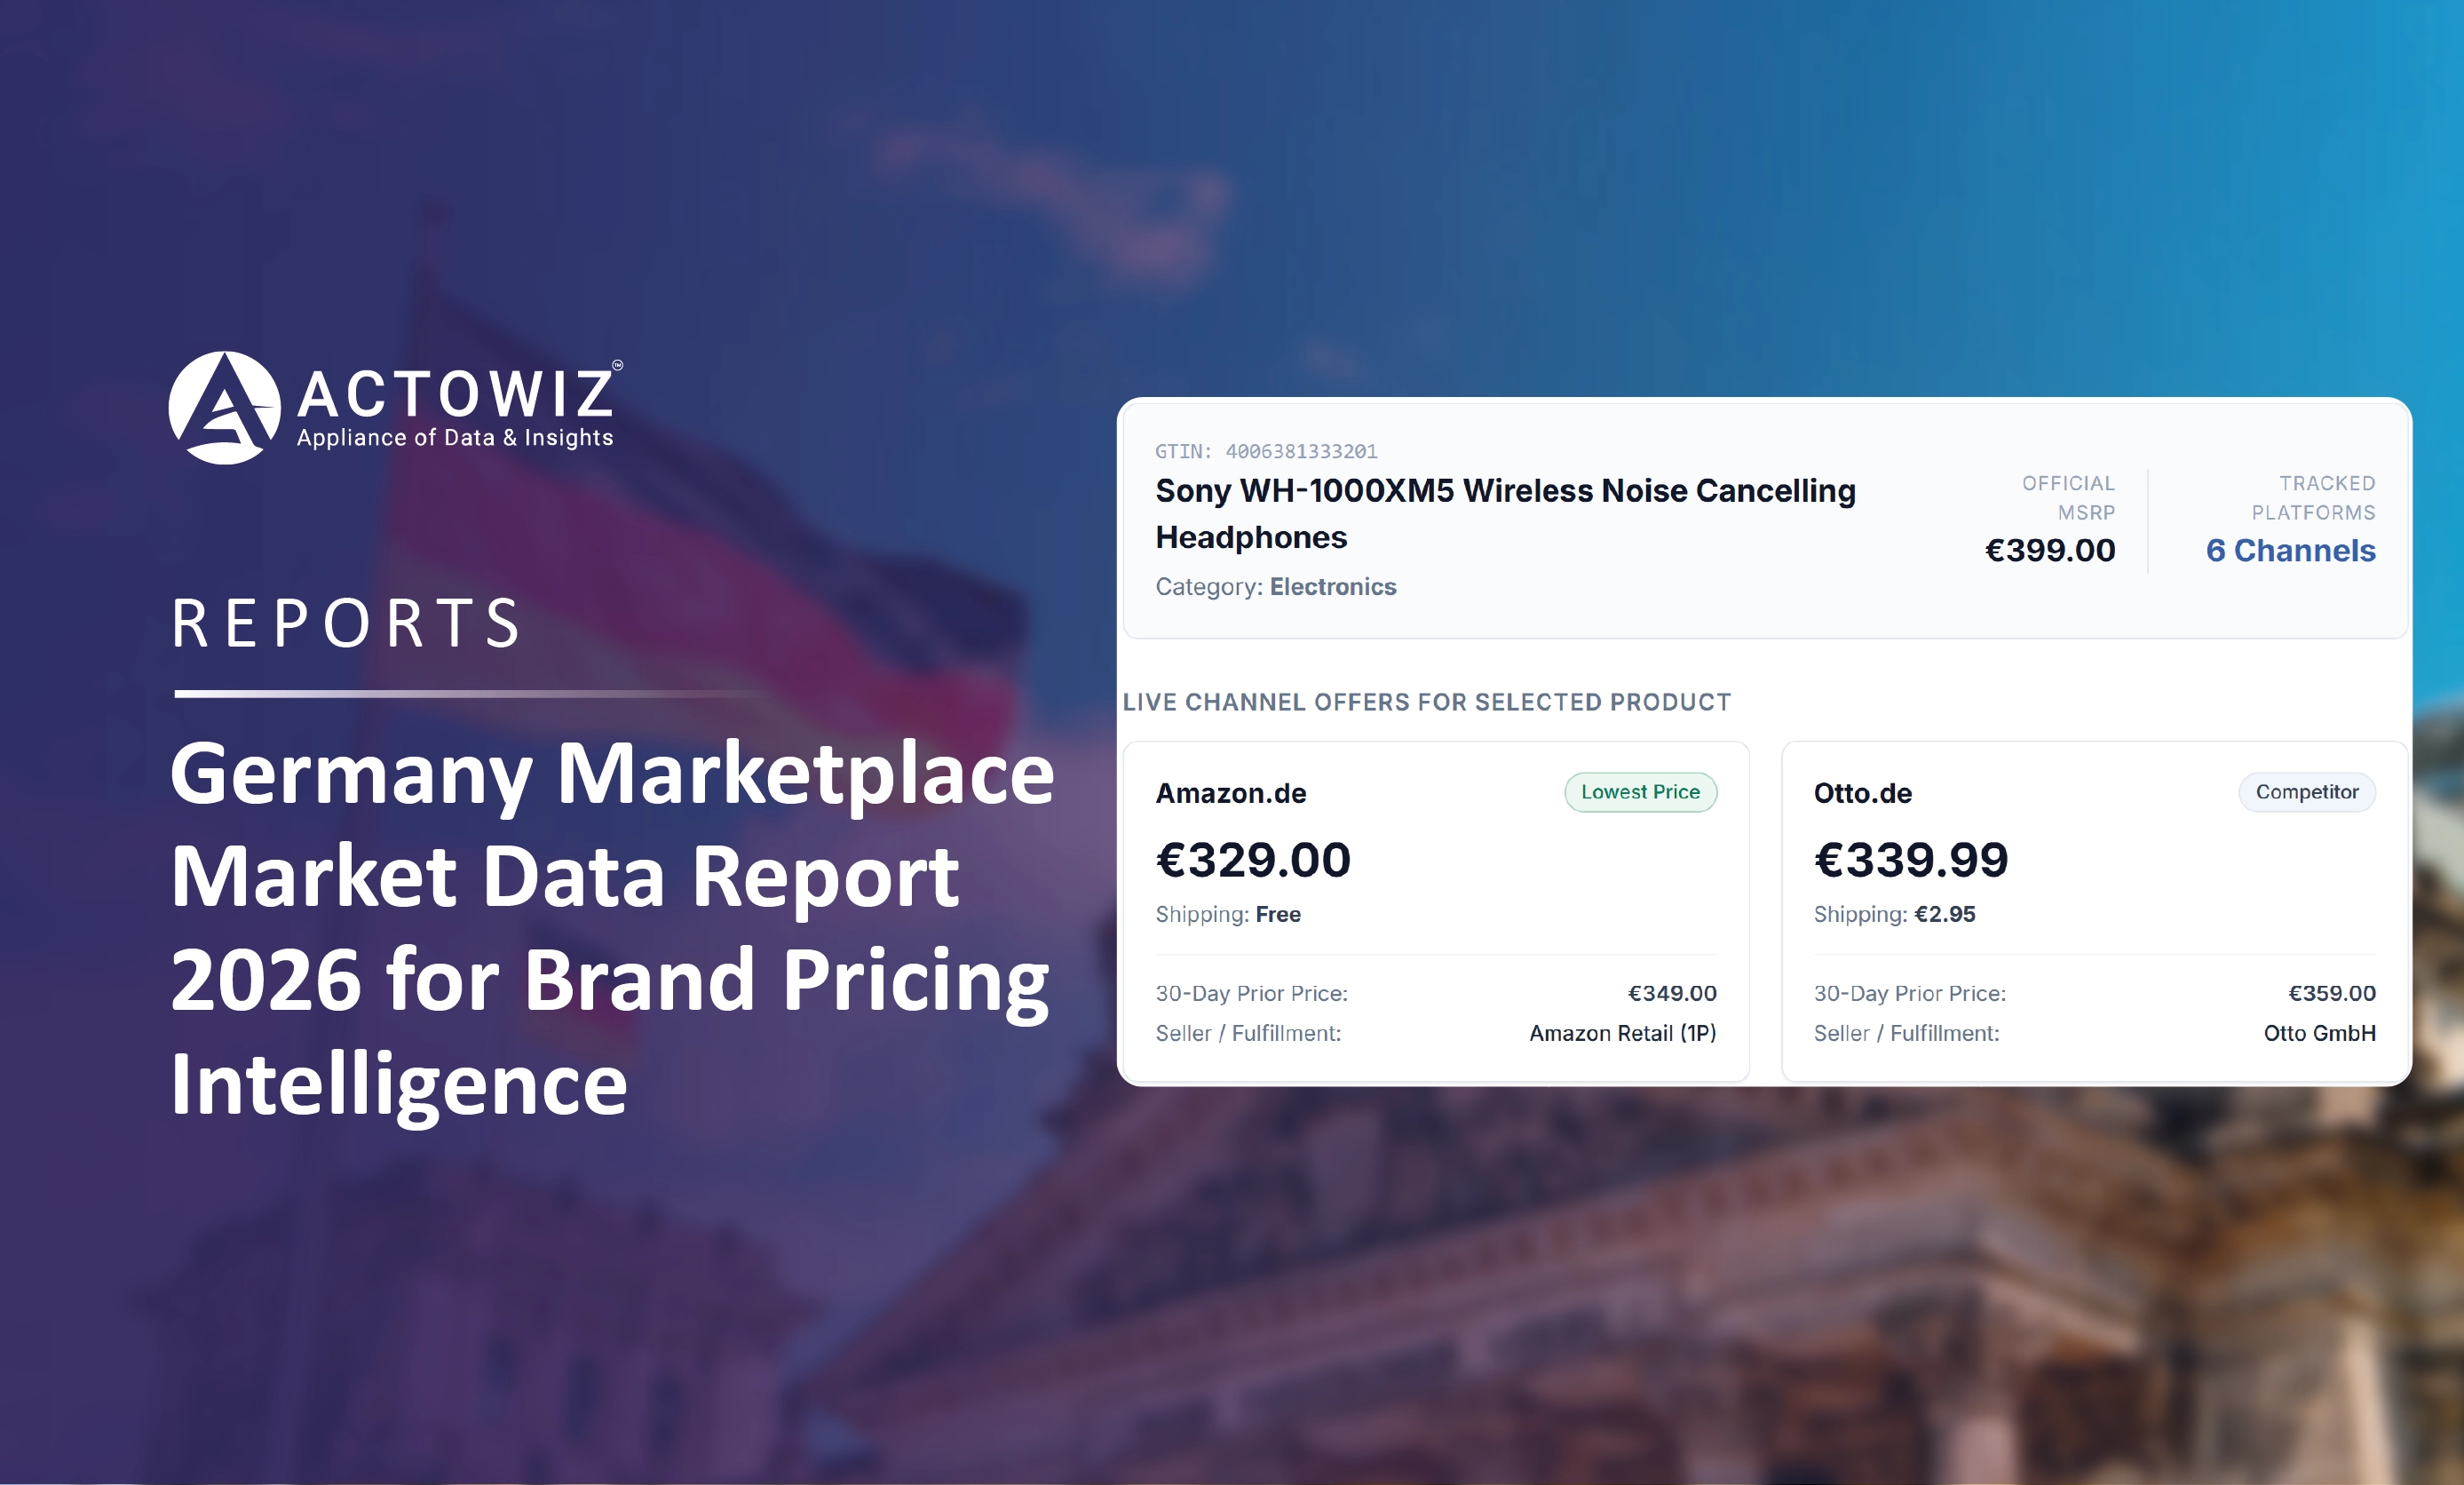
German marketplace data report 2026: online retail size, Amazon.de, Otto, Kaufland and Zalando price signals, PAngV rules and peak seasons.
Germany is Europe's most marketplace-heavy large e-commerce market, and that makes German marketplace data the core input for any brand pricing team selling there. The numbers in this report come from published sources: the HDE Online-Monitor 2026, the bevh annual figures and German and EU legal texts.
The short answer: German online retail reached about EUR 92.3 billion in 2025 (HDE), marketplaces take 56% of e-commerce goods revenue (bevh) and Amazon.de holds roughly 63% of online sales. Brand pricing teams therefore need daily, seller-level data from Amazon.de, Otto, Kaufland.de, Zalando, eBay.de and idealo, with VAT-inclusive prices, Grundpreis and 30-day prior prices.
This report is written for brands in consumer electronics, home & DIY, fashion, beauty and FMCG. Each section ends with a table you can reuse in an internal brief. Where we do not yet have a cited figure, you will see a yellow placeholder for the Actowiz dataset value.
Two industry bodies publish the most quoted German e-commerce numbers, and they measure slightly differently. The HDE Online-Monitor 2026 (prepared by IFH Köln for the German Retail Federation) reports net B2C online revenue of EUR 92.3 billion in 2025, up 3.9% on 2024, and forecasts EUR 96.3 billion for 2026. HDE puts the online share of retail at 13.5% in 2025, rising to a forecast 13.8% in 2026.
The bevh 2026 presentation (German E-Commerce and Distance Selling Trade Association) measures goods revenue including VAT and reports EUR 83.1 billion in 2025, up 3.2%, with nominal growth of 3.8% expected for 2026. The difference is definitional, not a contradiction: pick one source per board slide and say which one you used.
For pricing teams the message is that growth is moderate, single-digit and steady. In a market growing at around 4% a year, share gains come from price position, availability and content rather than from the market lifting everyone. That is why price and assortment data matters more in Germany than raw traffic.
| Year | HDE online revenue, net (EUR bn) | HDE online share of retail | bevh e-commerce goods revenue, incl. VAT (EUR bn) | Actowiz tracked marketplace listings (DE) |
|---|---|---|---|---|
| 2023 | 85.5 | 13.2% | Not used in this report | Pending |
| 2024 | 88.8 | 13.4% | 80.6 | Pending |
| 2025 | 92.3 (+3.9%) | 13.5% | 83.1 (+3.2%) | Pending |
| 2026 | 96.3 (forecast) | 13.8% (forecast) | +3.8% nominal (forecast) | Pending |
Marketplaces are now the default route to the German online shopper. The bevh figures show online marketplaces generating EUR 46.2 billion in 2025 – 56% of e-commerce goods revenue – and growing 4.9%, faster than the market. Online pure players took 28%, multichannel retailers 12% and manufacturers selling direct 3.4%. HDE reaches a similar picture: marketplaces hold about 56.7% of online sales, and Amazon.de's combined share (own retail plus marketplace) is 63.3%.
Beyond Amazon.de, each platform plays a different role. OTTO's company site states more than 6,200 marketplace partners and more than 12 million active customers. Kaufland.de runs a growing marketplace that now spans several European countries (onlinemarktplatz.de). Zalando dominates fashion and runs a partner programme next to its own retail. eBay.de remains important for electronics, parts and refurbished goods. MediaMarkt and Saturn combine stores, online shops and a marketplace for electronics. idealo and Check24 are not retailers but price comparison platforms where shoppers check the lowest offer before buying – verify current marketplace programmes for each before scoping.
| Platform | Role for brands | Key data to track | Cited fact |
|---|---|---|---|
| Amazon.de | Largest channel; own retail + third-party sellers | Buy Box price and seller, offer count, Prime / delivery, BSR, coupons | Amazon total ~63.3% of online sales 2025 (HDE) |
| Otto (otto.de) | Full-range marketplace, strong in home, furniture, electronics | Seller price, delivery cost and time, strike-through price, ratings | 6,200+ partners, 12m+ active customers (OTTO) |
| Kaufland.de | Fast-growing general marketplace | Offer price per seller, shipping, unit price, stock signal | Active in 7 countries, more planned (onlinemarktplatz.de) |
| Zalando | Fashion, shoes, beauty; retail + partners | Price, sale price, size availability, partner vs Zalando offer | Pending |
| eBay.de | New, refurbished, B-stock, grey market | Fixed-price offers, seller type, condition, shipping | Pending |
| MediaMarkt / Saturn | Electronics omnichannel | Online price vs marketplace seller, availability by store | Pending |
| idealo / Check24 | Price comparison, sets the visible 'lowest price' | Lowest offer, shop count, price history, delivery cost | Pending |
German online demand is concentrated in a few categories, and the pricing logic differs in each. HDE estimates that fashion & accessories made up 22.9% of 2025 online volume (EUR 21.2 billion) and consumer electronics 21.3% (EUR 19.7 billion). In both categories online already takes a large share of all category sales – about 44% in fashion and 39% in electronics – so online prices effectively set the market price.
FMCG is the fastest mover. HDE reports FMCG online growth of 10.4% in 2025, while online still accounts for only about 5% of FMCG sales. bevh shows food (+5.5%), drugstore (+4.6%) and DIY & flowers (+4.9%) growing faster than electronics (+1.4%). For beauty and FMCG brands this means newer channels, more resellers and more unit-price comparisons – and a higher need for pack-size matching.
Home & DIY sits in between: HDE puts home & living at EUR 8.1 billion and DIY & garden at EUR 3.3 billion online. Long product titles, many variants and bulky delivery charges make matching and landed-price comparison the main data challenges here.
| Category | Online size 2025 (source) | Growth 2025 (bevh) | Main pricing signal for brands |
|---|---|---|---|
| Consumer electronics | EUR 19.7bn, 38.9% online share (HDE) | +1.4% (electronics & telecom) | Buy Box price, UVP gaps, idealo lowest price |
| Fashion & accessories | EUR 21.2bn, 44.2% online share (HDE) | +3.5% (clothing) | Sale depth, size availability, prior price |
| Home & living | EUR 8.1bn (HDE) | +3.3% (furniture, lamps, decor) | Landed price incl. freight, variant match |
| DIY & garden | EUR 3.3bn (HDE) | +4.9% (DIY & flowers) | Seasonal price moves, delivery cost |
| FMCG / drugstore / beauty | EUR 13.4bn FMCG, +10.4% (HDE) | +4.6% drugstore, +5.5% food | Grundpreis (EUR per kg / l), multipacks |
German price displays are regulated, which is good news for data teams: the fields are standardised and visible. The Price Indication Ordinance (Preisangabenverordnung, PAngV) requires consumer prices to be shown as total prices including VAT, and in most cases a unit price (Grundpreis) per kilogram, litre, metre or similar unit next to the total price for goods sold by weight, volume, length or area.
Since 28 May 2022, PAngV §11 also implements the EU Omnibus rule (Directive (EU) 2019/2161): when a seller announces a price reduction, it must state the lowest total price it charged in the 30 days before the reduction. On German pages this usually appears as a strike-through or 'lowest price of the last 30 days' line. Capturing this field daily lets brands see whether a reseller's discount is real and how deep it is against the true prior price.
For brand teams the practical point is simple: collect the total price, the Grundpreis, the reference price type (prior price, UVP or no reference) and delivery cost as separate fields. Mixing them is the most common reason German price dashboards disagree. This report does not give legal advice – speak to your counsel about your own obligations.
| Field | What it shows on German pages | Why brand pricing teams care |
|---|---|---|
| total_price_eur | Final price incl. 19% or 7% VAT | Like-for-like comparison across channels |
| grundpreis_eur_per_unit | Price per kg / l / m etc. | Pack-size and multipack comparisons in FMCG, beauty, DIY |
| prior_price_30d_eur | Lowest price in 30 days before a reduction | Real discount depth during promotions |
| uvp_eur | Manufacturer's recommended retail price (where shown) | Gap to recommended price by seller |
| delivery_cost_eur | Shipping or freight charge | Landed price; bulky home & DIY items |
| seller_count / buy_box_seller | Number of offers and winning seller | Reseller pressure and channel conflict |
German price calendars have three big peaks. Amazon's Prime Day 2026 ran from 23 to 26 June in Germany (mobiflip), earlier than the traditional July slot. Black Friday and Cyber Monday follow in late November; most German retailers stretch this into a 'Black Week'. HDE expected EUR 5.8 billion in revenue across Black Friday and Cyber Monday 2025, its first forecast decline (just under 2%) since tracking began in 2016 (HDE via HV Bayern).
Christmas is the largest season. HDE forecast EUR 126.2 billion of November–December 2025 retail revenue, with EUR 22.2 billion online, up 3.3% (HDE Christmas forecast). In HDE's Black Friday survey (IFH Köln, October 2025), 54% of online shoppers said they use Black Friday for Christmas buying – so prices set in late November often stay sticky into December.
Because of the 30-day prior-price rule, a price raised in October directly affects the reference price a seller can show in November. Brands that start daily tracking at least 30–45 days before each event can see this build-up. Black Friday 2026 falls on 27 November and Cyber Monday on 30 November.
| Event (Germany) | 2026 timing | What to watch in the data |
|---|---|---|
| Prime Day | 23–26 June 2026 (done) | Amazon.de deal prices vs Otto, Kaufland, MediaMarkt reaction |
| Pre-Black-Week window | Late October – mid November | Price rises that reset the 30-day prior price |
| Black Friday / Black Week | Week to 27 November 2026 | Discount depth vs prior price, Buy Box churn, stock-outs |
| Cyber Monday | 30 November 2026 | Electronics and fashion follow-on cuts |
| Christmas | December 2026 | Delivery cut-off dates, price stickiness, availability |
| Year-end sales | After 26 December / January | Clearance prices, seasonal fashion and DIY |
Cross-border supply is now a pricing factor brands cannot ignore. HDE estimates that foreign online providers account for about 11.8% of German online volume, roughly EUR 10.9 billion. Temu and Shein together reached an estimated EUR 4.7 billion in 2025, up from about EUR 3.0 billion in 2024, with 16 million German online shoppers buying from them.
bevh adds that platforms with origin in China contributed EUR 791 million of the EUR 2.58 billion market growth in 2025 – about 30%. For brands this shows up in two ways: low-price lookalikes in the same search results, and cross-border sellers on Amazon.de, Kaufland.de and eBay.de offering the brand's own products with different delivery times and prices.
Data teams should therefore tag every offer with seller country (where shown publicly), delivery time and fulfilment type. That lets a pricing director separate domestic authorised resellers from cross-border and grey-market offers before taking action.
| Signal | Cited figure (2025) | Data field to capture |
|---|---|---|
| Foreign providers' share of German online volume | ~11.8%, ~EUR 10.9bn (HDE) | seller_country, ships_from |
| Temu + Shein revenue in Germany | ~EUR 4.7bn, preliminary (HDE) | Category price bands vs lookalikes |
| Temu / Shein German buyers | 16.0m (HDE) | Search-result share by seller type |
| China-origin platforms' share of market growth | ~30% (bevh) | delivery_days, fulfilment_type |
| Cross-border offers on your own SKUs | Pending | seller_id, offer_price, condition |
A useful German marketplace data feed starts with a fixed SKU list matched by EAN/GTIN, brand and model number, then collects the same field set from each platform at a set cadence. Daily is the norm for electronics and fashion; twice a day or hourly makes sense around Prime Day and Black Week. FMCG and beauty brands usually add Grundpreis and pack size so multipacks can be compared fairly.
Data protection is simpler than many teams expect when the scope is right. The GDPR and the German Federal Data Protection Act (BDSG) apply to personal data. Product prices, offers, seller business names and public ratings are business data; reviewer names or private seller details are not needed for pricing and should be left out. Actowiz collects public business data only, respects site terms and does not log in. This is not legal advice – speak to your counsel.
| Spec item | Typical choice for German brands | Notes |
|---|---|---|
| Coverage | Amazon.de, Otto, Kaufland.de, Zalando, eBay.de, MediaMarkt / Saturn, idealo | Add category specialists as needed |
| Matching | EAN / GTIN first, then brand + model + pack size | Manual QA on unmatched items |
| Cadence | Daily; hourly or twice daily in event windows | Start 30–45 days before Black Week |
| Fields | Total price, Grundpreis, prior price, UVP, delivery cost, seller, Buy Box, stock | Separate fields, never merged |
| Delivery | API, CSV / JSON, S3, Snowflake, BigQuery | Dashboards via Actowiz Metrics |
| QA and SLA | Automated checks + sample review; agreed delivery time | Sample dataset within 24 hours |
Germany's online market is large, steady and dominated by marketplaces: about EUR 92 billion in 2025, 56% of goods revenue through marketplaces and Amazon.de at roughly 63% of online sales. Growth is moderate, so brands win on price position, availability and clean offers – and German law makes the key price fields visible for anyone who tracks them properly.
The brands that act fastest combine daily German marketplace data with event-window tracking and a clear view of cross-border sellers. Download the full report with your company email, or book a scoping call – share your use case, platforms, categories and SKU volume and we will send a sample dataset within 24 hours.
It is public product, price, seller and availability data from German marketplaces such as Amazon.de, Otto, Kaufland.de, Zalando and eBay.de, normalised in EUR so brands can compare prices and resellers across channels.
HDE forecasts EUR 96.3 billion net online revenue for 2026, after EUR 92.3 billion in 2025. bevh, which counts goods revenue including VAT, expects about 3.8% nominal growth in 2026.
PAngV §11 requires sellers announcing a reduction to show their lowest price of the previous 30 days. Tracking it shows real discount depth and price rises before events like Black Week.
Start with Amazon.de, then Otto, Kaufland.de and your category leader (Zalando for fashion, MediaMarkt / Saturn for electronics), plus idealo for the lowest visible price.
Prices, offers and seller business names are business data. Leave personal data such as reviewer names out of scope. Actowiz collects public business data only – speak to your counsel for your case.
Daily for most categories, and hourly or twice daily during Prime Day, Black Week and Christmas windows.
Our web scraping expertise is relied on by 4,000+ global enterprises including Zomato, Tata Consumer, Subway, and Expedia — helping them turn web data into growth.
Watch how businesses like yours are using Actowiz data to drive growth.
From Zomato to Expedia — see why global leaders trust us with their data.
Backed by automation, data volume, and enterprise-grade scale — we help businesses from startups to Fortune 500s extract competitive insights across the USA, UK, UAE, and beyond.
We partner with agencies, system integrators, and technology platforms to deliver end-to-end solutions across the retail and digital shelf ecosystem.
Plan multi-country ecommerce data from Singapore: Shopee, Lazada and grocers in 6 SEA markets, SGD-normalised, one schema.
Sensitive Skin Skincare Product Data API helps brands track cleansers, serums, moisturizers, and sunscreens with structured product data.
German marketplace data report 2026: online retail size, Amazon.de, Otto, Kaufland and Zalando price signals, PAngV rules and peak seasons.
Whether you're a startup or a Fortune 500 — we have the right plan for your data needs.